TL;DR: The best general contractor for an insurance rebuild in Royse City is licensed with the Texas Department of Licensing and Regulation, holds IICRC credentials for the trades your claim touches (water, fire, mold), writes an itemized Xactimate estimate your adjuster can reconcile line by line, and handles both the mitigation and the reconstruction under one contract so nothing falls through the gap between two companies. Confirm all four before you sign anything.
If your adjuster just approved a water or fire claim and handed you a scope of loss, the contractor you pick next decides how smooth the rest of this goes. A good rebuild partner reads that scope, flags what’s missing, and rebuilds to it without you chasing two separate companies for one repair. A bad one either underbids to win the job and comes back with supplements every other week, or disappears between the demo and the drywall. In Royse City and across Rockwall and Hunt counties, where hail and burst-pipe claims both run through the same handful of restoration and construction firms, here’s what actually separates a contractor built for insurance work from one that just takes insurance jobs when they land.
What Makes a Contractor Right for an Insurance Rebuild, Specifically?
An insurance-ready contractor writes estimates in the same software your adjuster uses, documents damage the way a claims file requires, and has done enough of these jobs to know what gets denied versus what gets paid. That’s different from general remodeling experience.
Most remodeling contractors are excellent at kitchens and additions priced against a homeowner’s budget. A claims rebuild is priced against a carrier’s scope of loss, using line-item codes (Xactimate pricing) that both sides recognize. A contractor who doesn’t write estimates that way will underbid the job, then have to come back asking for more money mid-project, or eat the difference and cut corners to make it work.
Ask directly: “Do you write your estimates in Xactimate, and can you show me a sample?” If the answer is a blank look, keep looking.
Insurance Restoration Contractor vs. a Regular General Contractor: What’s the Real Difference?
An insurance restoration contractor is built around the claims process from day one; a regular general contractor treats an insurance job as just another remodel with a different funding source. That distinction shows up in three places: documentation, code-upgrade knowledge, and who talks to the adjuster.
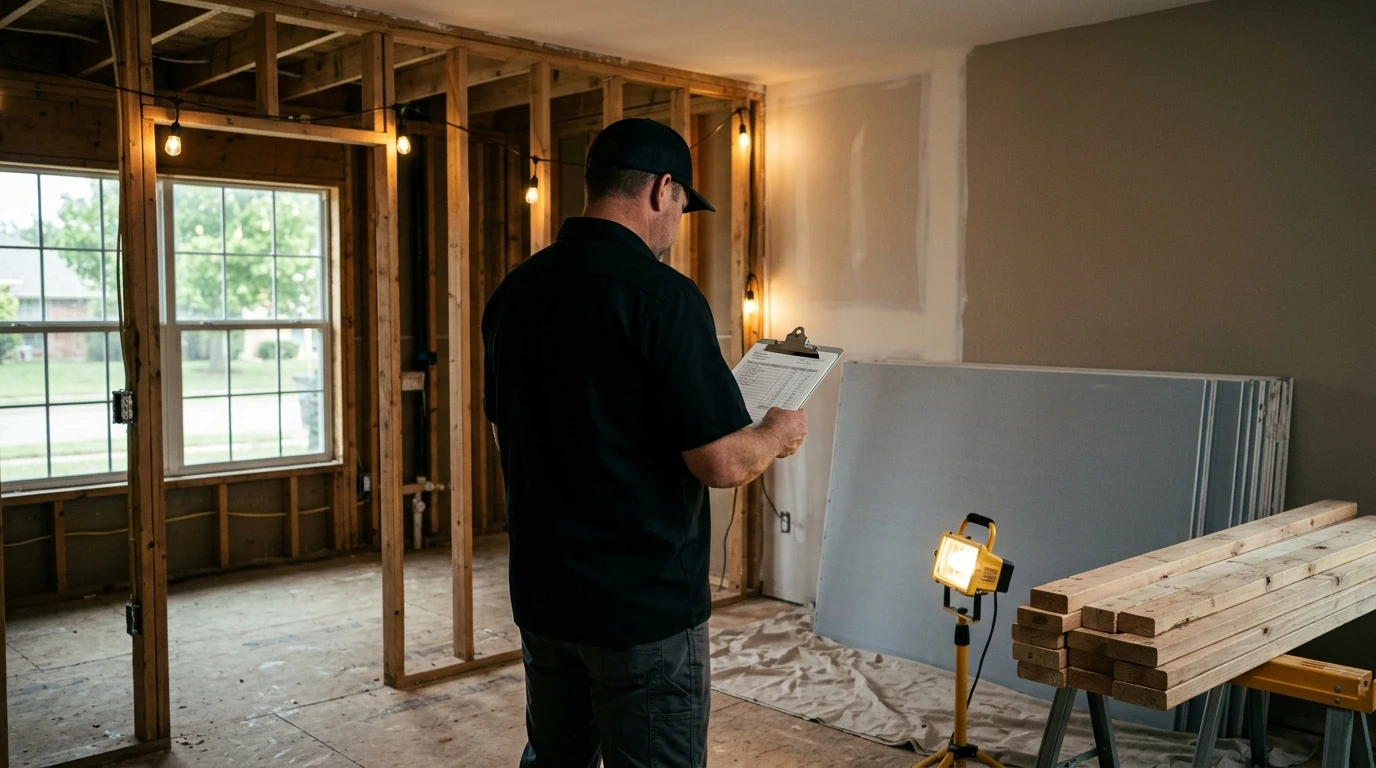
A restoration-focused contractor photographs and moisture-maps the damage before demo starts, because that documentation is what justifies the scope later. They also know when local or Texas building code requires an upgrade beyond simple like-for-like replacement (a GFCI circuit added where there wasn’t one, for example) and can write that into a supplement instead of eating the cost. A generalist contractor often finds those requirements mid-job, after the budget is already set.
That’s the gap Reign Restoration is built to close: the same company that performs the water damage restoration or fire damage restoration mitigation also runs the general contracting and reconstruction phase, under one insurance file.
Who Coordinates With the Insurance Adjuster on a Rebuild?
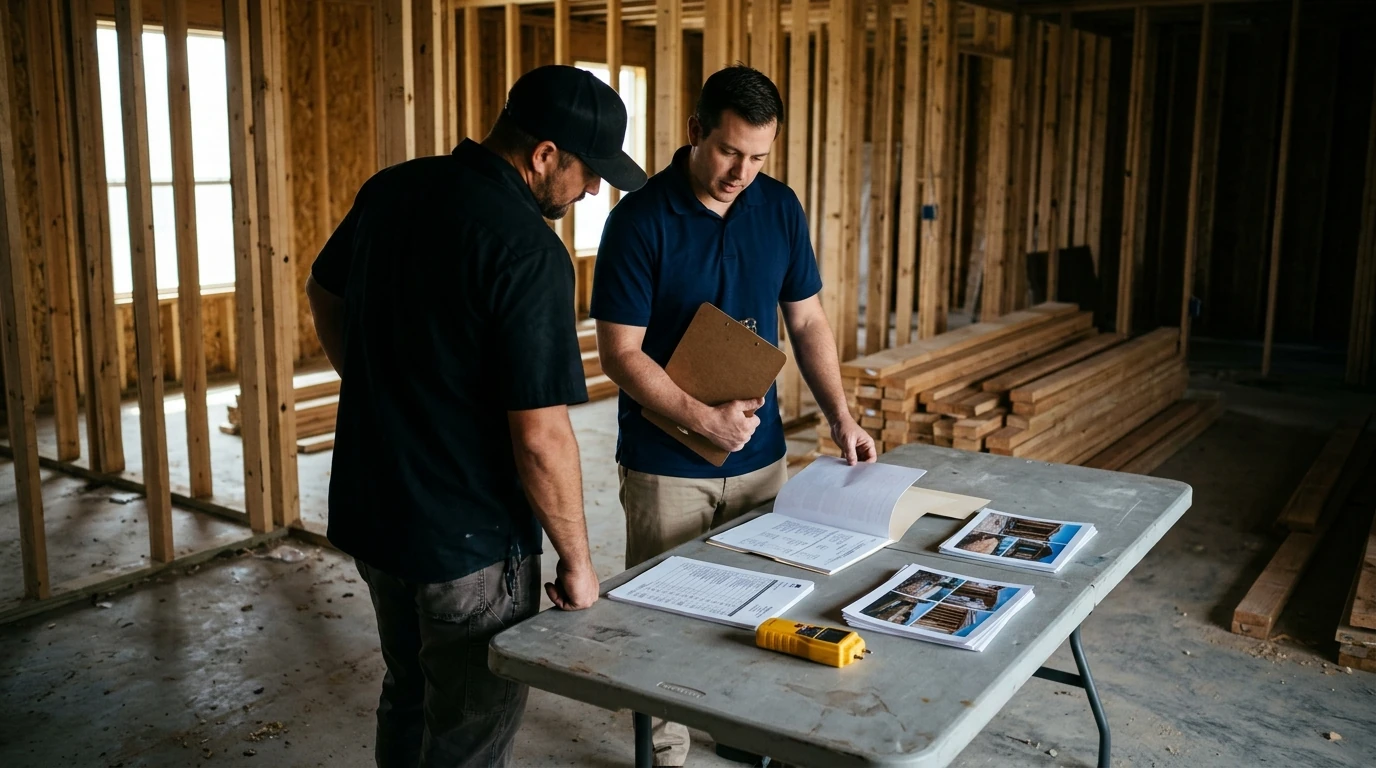
Whoever performed the mitigation should be the one talking to the adjuster during the rebuild, because they’re the one holding the original moisture readings, photos, and category/class documentation the scope is based on. Handing that file to a separate rebuild contractor means re-explaining the loss, often from scratch.
In practice this means one point of contact walks the adjuster through the property, answers questions about what was removed and why, and submits any supplement request with the documentation attached, not a verbal estimate. Reign Restoration handles that coordination directly as part of its general contracting scope, which is the model described in our water damage insurance claim guide for Texas homeowners.
What Belongs in an Itemized Estimate, and What’s a Supplement?
An itemized estimate lists every material, labor hour, and line-item code tied to the approved scope, so you and the carrier can both see exactly what’s being paid for and why. A supplement is a follow-up request for additional covered work discovered once demo opens the walls, like hidden water migration or code-required upgrades.
Before you sign a contract, ask for the itemized breakdown, not a one-page lump-sum quote. A lump sum hides whether the drywall, texture, paint, trim, and flooring are each priced to match what the adjuster approved, and it makes a legitimate supplement harder to prove later. Supplements are normal on insurance rebuilds, especially after a hail or pipe-burst loss where damage is often worse once materials come out. What’s not normal is a contractor who treats every supplement as a surprise rather than documenting it against photos and moisture readings as the job progresses.
For a real example of how a scope grows from first inspection to final supplement, see our water damage rebuild case study.
Should Mitigation and the Rebuild Be One Company, or Two?
One company, when that company is actually licensed and staffed for both phases, almost always produces a cleaner claim and a faster timeline than splitting mitigation and reconstruction between two firms. The handoff between separate companies is where documentation gets lost and scopes get re-argued.
When mitigation and rebuild sit with different companies, the rebuild contractor often has to re-verify drying logs, moisture readings, and the original category of the water loss before they’ll warranty their own work over it, which the IICRC S500 standard requires drying be verified against in the first place. That re-verification costs time and sometimes a second inspection fee. One contractor carrying both phases, which Reign Restoration does across water damage restoration, fire damage restoration, and reconstruction, skips that step entirely because the same drying logs feed straight into the rebuild scope.
What to Ask Before You Sign a Rebuild Contract in Texas
Before signing, confirm the contractor’s license is active with the Texas Department of Licensing and Regulation, get the itemized estimate in writing, and get a straight answer on who files the supplement if one comes up.
A short list worth going through line by line:
- Is your license number current, and can I verify it myself?
- Will you write the estimate in Xactimate or a comparable line-item format?
- Who talks to my adjuster if the scope needs to change mid-job?
- Do you carry the IICRC credentials for the trade involved (water, fire, mold), or is that a subcontractor?
- What’s the payment schedule, and does it track with insurance disbursement draws rather than requiring full payment up front?
If a contractor can’t answer two or more of those cleanly, that’s reason enough to call someone else. For the mitigation side of vetting a company more broadly, our guide to choosing a restoration company covers the questions that apply before the rebuild even starts.
Reign Restoration is an IICRC Certified Firm licensed under Texas license MRC2276, based in Royse City and serving Rockwall, Fate, Rowlett, and the surrounding communities. Request a written rebuild estimate from Reign Restoration before you sign anything, or call Reign Restoration at (214) 304-0621 to walk through your adjuster’s scope line by line.
About Reign Restoration
Reign Restoration is an IICRC Certified Firm (license MRC2276) based in Royse City, Texas, serving Rockwall, Fate, Rowlett, and the surrounding North Texas area around the clock. The company carries IICRC credentials in water, fire and smoke, and mold restoration, and pairs its mitigation work with in-house general contracting and reconstruction so claims move from first inspection to final rebuild under one contract. This post was prepared with the Reign Restoration team.
Video Transcript
If your insurance adjuster just approved a water or fire claim, the contractor you choose next decides how smooth your rebuild goes. A good rebuild partner reads your scope of loss, flags what’s missing, and builds to it without chasing two separate companies. Your contractor should write estimates in the same software adjusters use, so every line item can be checked and reconciled. Ask directly: does your contractor write estimates in Xactimate, and can they show you a sample before you sign anything? A true restoration contractor photographs and moisture-maps damage before demolition starts, because that documentation supports your claim later. They also know when local code requires upgrades beyond simple replacement, and document that properly instead of surprising you mid-project. Whoever handled the mitigation should keep talking to your adjuster during rebuild, since they hold the original photos and readings. One company handling both mitigation and reconstruction almost always means a cleaner claim and a faster timeline for your home. Before signing, ask for an itemized estimate, not a lump-sum quote, so every material and labor line matches what’s approved. Call Reign Restoration at (214) 304-0621 to schedule an assessment, and let an experienced rebuild partner guide your claim home.